China is ahead of the United States in the supply of humanoid robots
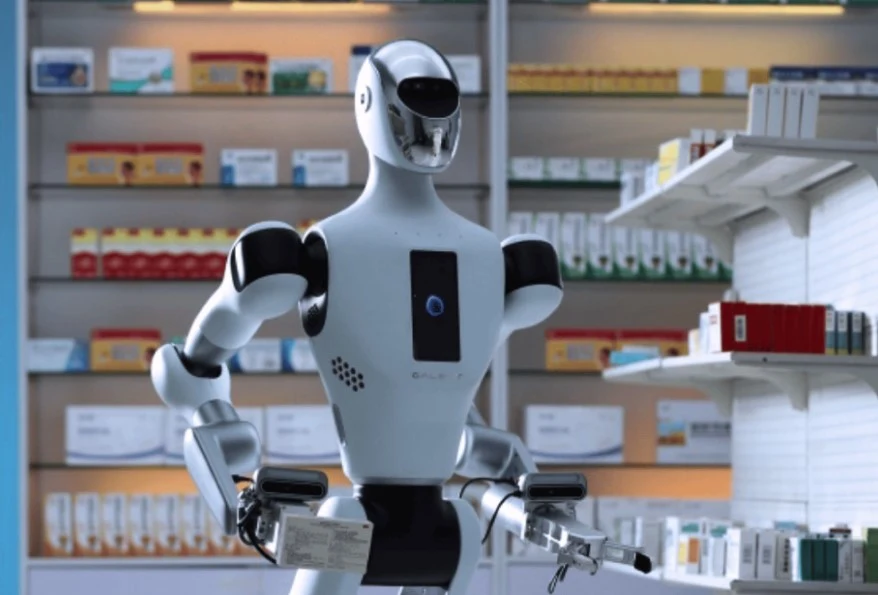
English translation from Unibot. Source published 2026-04-23.
Chinese companies developing humanoid robots are accelerating their entry into the real world and ramping up deployments, delivering systems to factories, airports and commercial facilities at a pace that is noticeably outpacing American competitors. Meanwhile, US startups continue to attract significantly higher valuations, highlighting the growing gap between scaling in the market and investor perception.
Data cited by CNBC shows that Chinese firms dominated global shipments of humanoid robots in 2025, occupying the top six positions in Omdia's ranking. There were only two companies from the USA in the top 10 - Figure and Tesla. At the same time, American teams are already placing robots in work environments.
Application examples include factory automation, airport operations, and semiconductor and medical industrial applications. AI2 Robotics, a Chinese startup with a reported valuation of about 20 billion yuan, has attracted industrial customers and says it has been chosen for use in factories over its American competitor. The company also deploys systems in public infrastructure, including airports.
This “hands-on” approach to deployment contrasts markedly with the valuation profiles of leading US companies in the humanoid robots segment. Figure is reported to have a valuation of at least $39 billion, while Apptronik previously reached $5 billion in 2026. By comparison, one of the most highly valued Chinese companies, Galbot, is valued at just over $3 billion, despite being actively commercialized.
Industry analysts attribute part of the gap to the way investors frame the opportunity itself. American companies are often positioned as generalist artificial intelligence platforms, while Chinese firms are often viewed more narrowly as providers of hardware-based industrial automation. This has implications for capital allocation: venture capital funding in the US is heavily skewed towards software development.
Geopolitical factors also influence investment flows. U.S. pension funds and other institutional investors have scaled back exposure to Chinese startups amid regulatory scrutiny and national security concerns. This has created space for investors from the Middle East to back venture capital funds and acquire Chinese-developed robotics solutions as part of their economic diversification strategies.
New investment patterns are starting to impact supply chains. U.S. buyers are increasingly ordering humanoid robot components from manufacturing sites including Shenzhen and then integrating them with software stacks developed domestically, according to industry consultants.
China's current strengths in large-scale manufacturing, shaped by sectors such as electric vehicles and drones, are now being applied to humanoid robotics. This speeds up readiness for mass production and allows deployments to begin earlier compared to US competitors, which remain more focused on research and systems integration.
As a result, a market with two trajectories is formed. Chinese firms are gaining operational experience and increasing deployments, while US firms are receiving higher valuations based on the potential of future platforms. Whether these paths converge will depend on how quickly mass adoption translates into sustainable revenue, and whether investor sentiment shifts in favor of proven field performance.